The rumor is that depreciation recapture comes due the year you close and kills the installment sale. For a straight-line residential rental that is wrong, but the ordering rule in Treas. Reg. §1.453-12 loads the 25% layer into your first payments, and a cost segregation study really does put recapture back in year one.
The penalty under §6654 is four separate quarterly bills, and a gain that closed in November still gets measured against the installment that came due on April 15. Form 2210 Schedule AI is how you match the installments to the month the money actually arrived.
December 31, 2026 is a hard wall only if you pay yourself on a W-2. A one-person Schedule C business opening its first plan can still make the full $24,500 employee deferral for 2026 as late as April 15, 2027.
The fourth installment for 2026 is due January 15, 2027, and whether you owe it comes down to one number. If you skipped the first three, December withholding fixes more of the penalty than a January check does.
A December equipment purchase is a timing move, not a discount. On $50,000 of equipment an S corp owner in the 24% bracket saves $9,600 of federal tax and is still out $40,400, and the deduction only counts if the machine is in service by December 31.
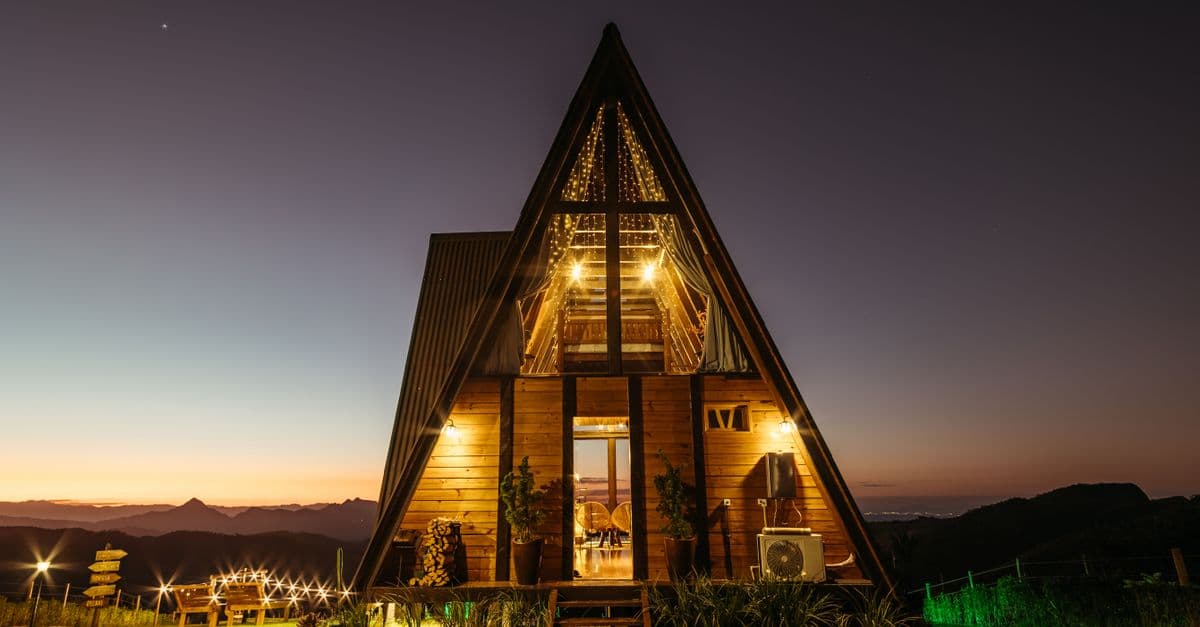
Your first Airbnb return turns on the date the listing went live, the gross figure on the 1099-K, and whether a first-year loss can touch your W-2 income. On the cabin below, that last one is worth $12,398.
A 15% ESPP discount is about 17.6% guaranteed on money tied up for an average of three months, before any lookback. Holding the shares two years for the tax break saves about $190 per purchase and puts $12,660 in one stock.
A rental that closes December 30 is taxed on the 2026 return, due in April 2027. One that closes January 5 is taxed a year later. On the sale below, the difference is $49,464 of tax and when it is due.
Most landlords owe these forms and never send them. For 2026 payments the trigger is $2,000 instead of $600, the roofing company is exempt, and the plumber you paid by credit card was already reported by somebody else.
A tender offer prices every share at the same number, and the tax code does not. The same $140,000 of proceeds leaves you with $115,748 or $73,794 depending on whether you sell stock you already own or exercise an option to fill the allocation.
Nobody checks the land split on a rental depreciation schedule, and it rides every year of the next 27.5. On a $525,000 duplex, the assessor's 40% land share against a documented 23% with the site work carved out is a $39,812 swing in first-year deductions.
A truck the company wrote off in full has a zero basis, so moving the title into your own name is a sale under §311(b), not a paperwork change. The $44,000 of ordinary income lands on your K-1 whether or not you pay the company a dollar for it.
Exercise and hold, watch the stock fall, and the wage income you already paid tax on comes back as a capital loss you can use $3,000 at a time. The recovery is real, it is almost entirely timing, and most of it closes on December 31.