
How to File Form 4547 Online in 2026 to Open a Trump Account and Claim the $1,000.
Treasury opened a Trump Account for every eligible child on October 1, 2026, but the $1,000 still only arrives if a parent files Form 4547. Here is how to file Form 4547 online in your IRS account, step by step.
A parent with a baby born in 2026 reads that Treasury just opened a Trump Account for their child automatically and assumes the $1,000 is on its way. It isn't. The account opened on its own on or about October 1, 2026, but the $1,000 pilot contribution only arrives if a parent elects it on Form 4547. Here is how to file Form 4547 online in 2026, inside your IRS account, in one short guided wizard.
A Trump Account is a new kind of individual retirement account opened for a child, created by the law the IRS calls the Working Families Tax Cuts, part of the One Big Beautiful Bill Act signed July 4, 2025, under IRC §530A. The pilot program pays a one-time $1,000 into the account for an eligible child, meaning a U.S. citizen with a valid Social Security number, born between January 1, 2025 and December 31, 2028. A baby born any time in 2026 qualifies. The money is not automatic. Form 4547 is the election that claims it, and you can do it from your couch.
Your child may already have an account
Sign-ups ran well behind what Treasury wanted. By July 30, 2026, the IRS had processed about 5.6 million Forms 4547 against roughly 73 million eligible children. So under temporary regulations published September 30, 2026, Treasury opened an auto account on or about October 1, 2026 for every child under 18 with a Social Security number who didn't already have one. A parent or guardian can claim that account through trumpaccounts.gov or the Trump Accounts app and manage it from there.
What the auto account does not do is elect the $1,000. That is still a separate election made on Form 4547 by the person who can claim the child, which in practice means a parent. If your child was born in 2025 through 2028 and you never filed, the account exists with nothing in it. Filing online takes the same wizard below, whether the account was opened by you or by Treasury.
How to file Form 4547 online in 2026
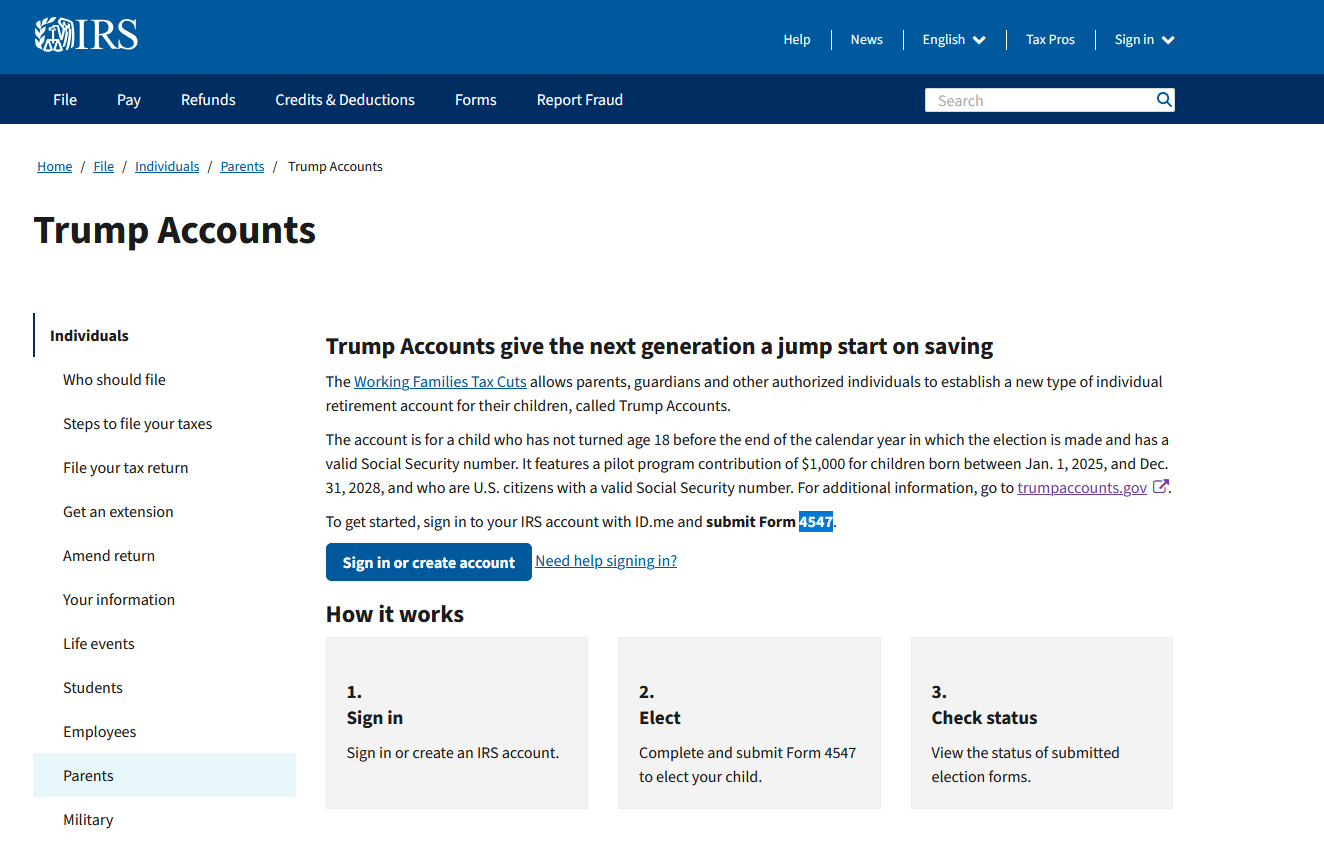
Go to irs.gov/trumpaccounts and sign in, or create an account, with ID.me. Inside your IRS Individual Online Account, open the Forms menu, choose Trump Accounts, and select Begin form. That starts a four-step wizard: Your information, Add child, Review and submit, and Confirmation. Here is the flow.
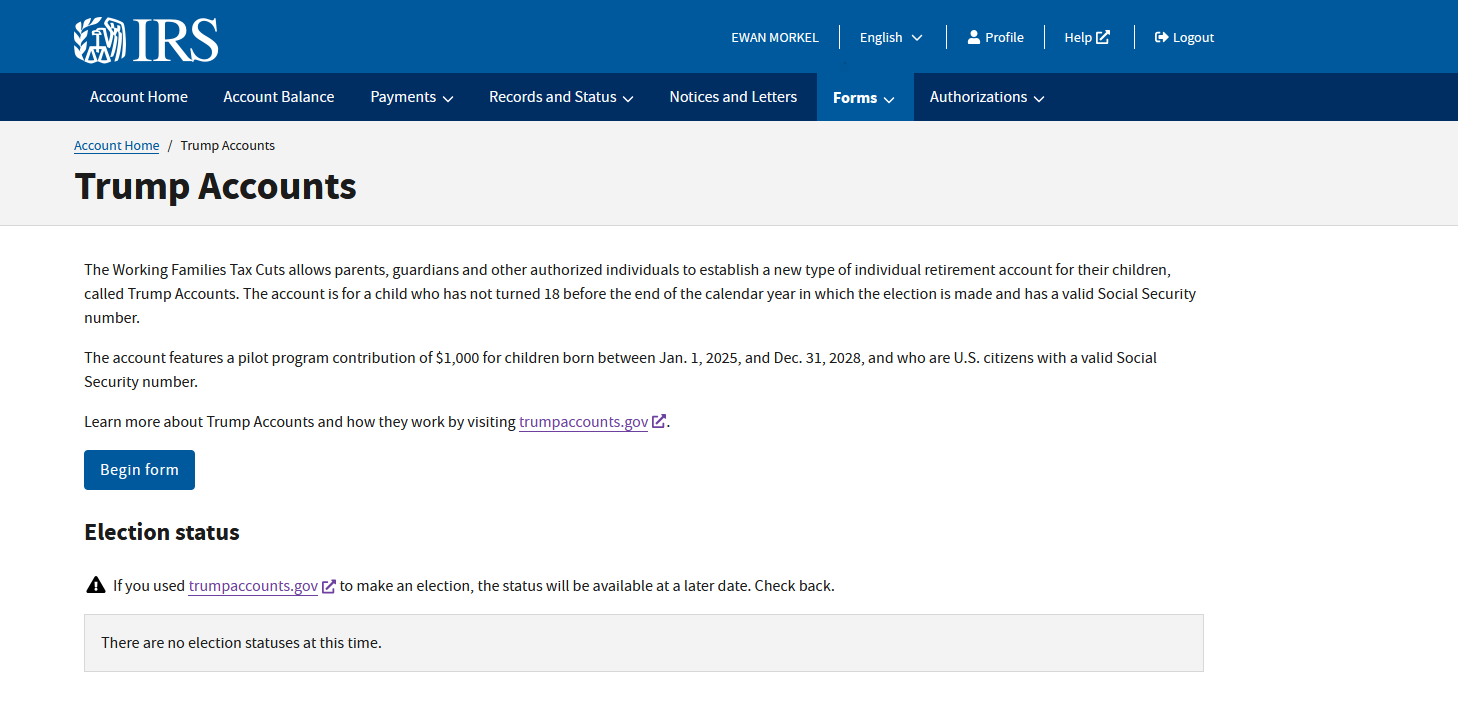
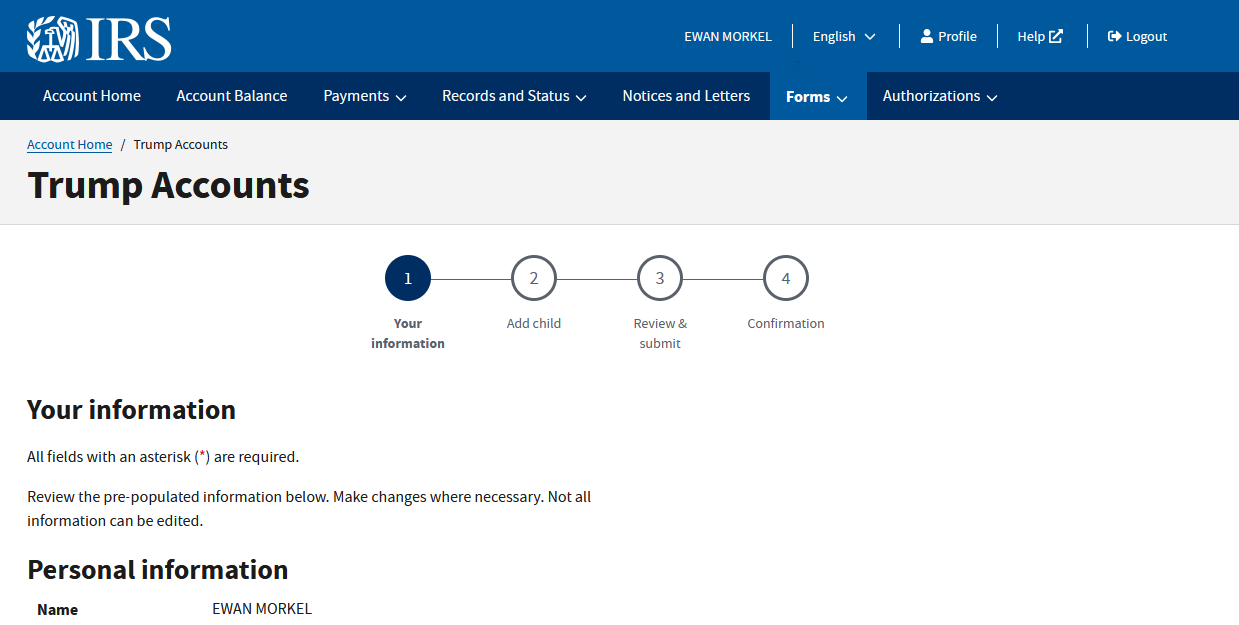
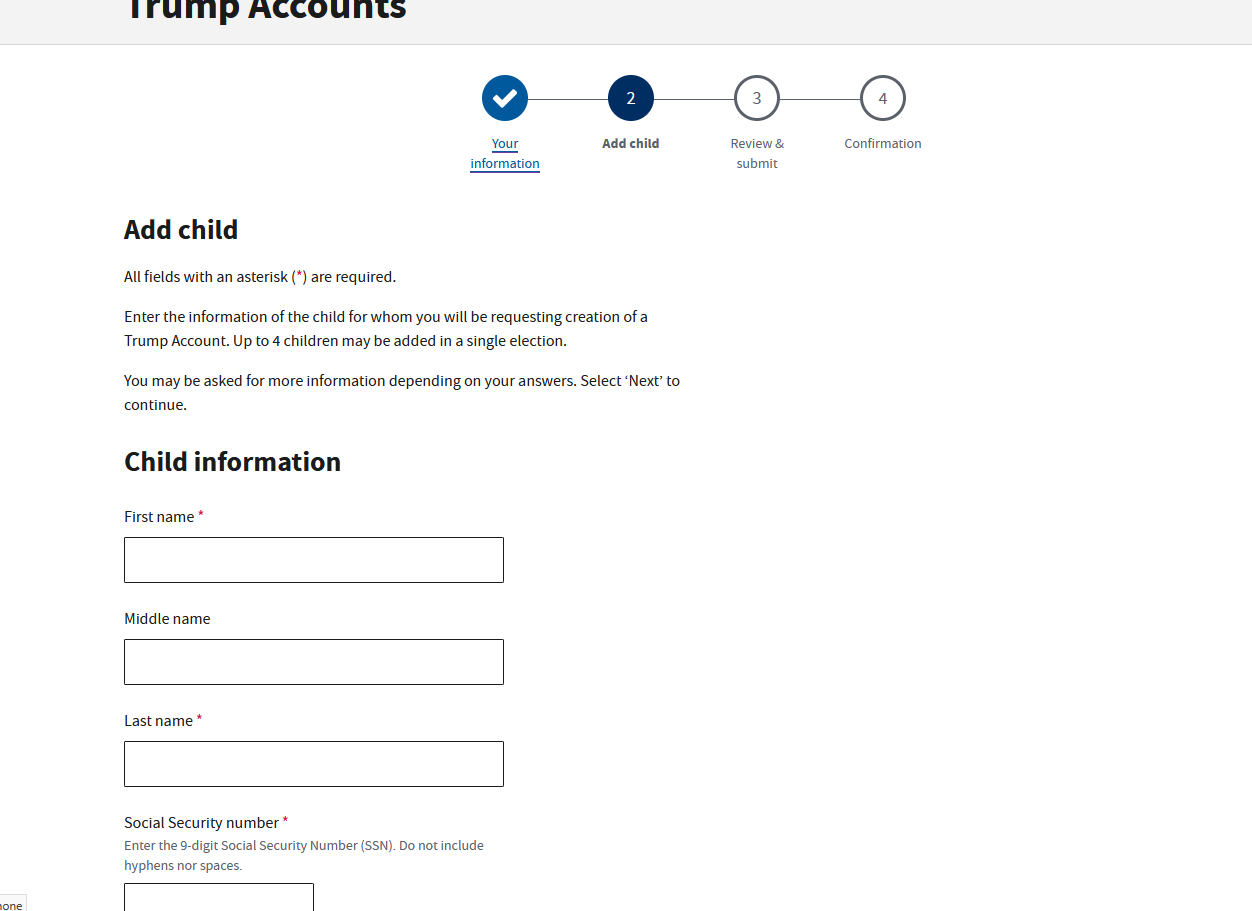
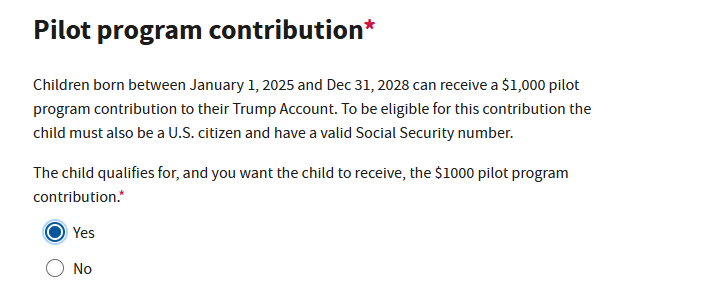
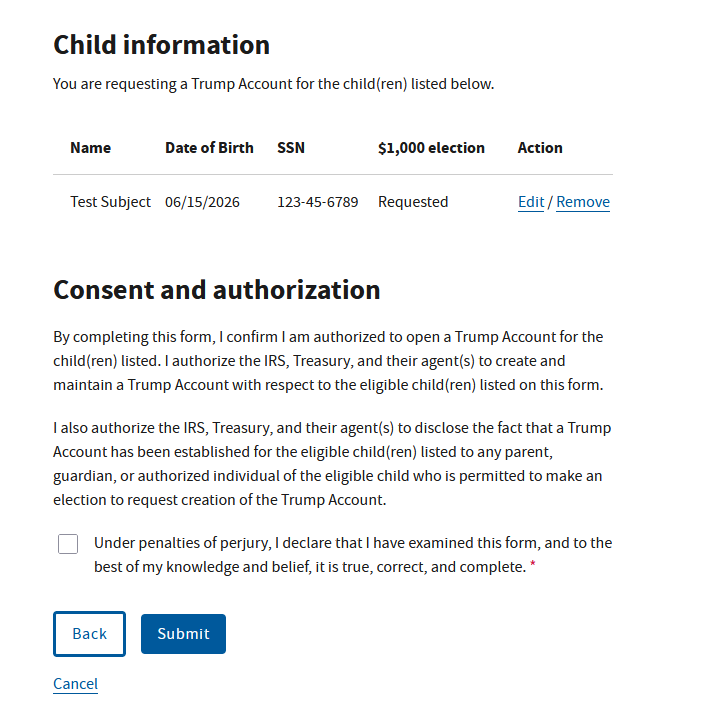
After the Add child step, the wizard moves to Review and submit, then shows a Confirmation. That is the whole election. You can come back later and check the Election status section on the Trump Accounts page in your account, though a status submitted through trumpaccounts.gov may take time to appear.
Who can file, and when the money lands
An authorized individual can open the account, meaning a parent, legal guardian, adult sibling, or grandparent, in that order of priority. The $1,000 pilot election, though, has to be made by someone who can claim the child, which in practice means a parent. The account is for a child who has not turned 18 before the end of the calendar year in which the election is made. Online isn't the only route: you can also attach Form 4547 to an e-filed Form 1040, or mail a paper Form 4547 to the address for your return at IRS.gov/PaperReturns. No contribution of any kind, including the $1,000, could post before July 4, 2026.
- One-time federal pilot contribution
- $1,000
- Your cost to file Form 4547 online
- $0
- Annual combined contribution limit (2026)
- $5,000
- Of which an employer may add under §128
- up to $2,500
- Earliest any contribution can post
- July 4, 2026
- Children allowed in one election
- up to 4
Tax year 2026. The $5,000 annual limit and the $2,500 employer limit under IRC §128 are indexed for inflation in later years. The $1,000 pilot contribution does not count against the $5,000 cap. Assumes a U.S.-citizen child with a valid SSN, born between January 1, 2025 and December 31, 2028.
What happens to the money
Trump Account dollars can only sit in a low-cost fund that tracks a U.S. equity index, so think an S&P 500 index fund, not hand-picked stocks. The money grows untouched until the child is grown, then the account becomes an ordinary traditional IRA, with normal IRA rules and the 10% early-withdrawal penalty under §72(t) before age 59½. The $1,000 from the government is pre-tax, so it and its earnings are taxed as ordinary income when distributed. A free $1,000 compounding for 18 years is a real head start, and it is the same early-and-tax-advantaged logic behind Peter Thiel's Roth IRA strategy and the backdoor Roth IRA once that child is earning. The hard part is not the strategy. It is remembering to select Yes.